

A business can report a profit and still struggle to pay bills on time. That happens because accounting profit and available cash measure different things. For U.S. owners, this report shows where money came from and where it went.
A cash flow statement shows how cash entered and left a business during a reporting period. It groups movements into operating, investing, and financing activities. The report helps owners judge liquidity, explain bank-balance changes, and see whether operations produce enough cash to support the business.
| Key point | What it means |
| Main purpose | Explains cash received and cash spent during a period |
| Main sections | Operating, investing, and financing activities |
| Reporting period | Commonly a month, quarter, or year |
| Operating presentation | Direct or indirect method under U.S. GAAP |
| Ending result | Net change explains movement from beginning to ending cash |
| Best use for owners | Checking liquidity, funding needs, and operational strength |
Key takeaways
- Profit does not automatically mean money is available in the bank.
- Operating activities show whether normal business activity generates cash.
- Investing activity often reflects equipment, property, or other long-term assets.
- Financing activity includes borrowing, repayments, owner funding, and similar transactions.
- Owners should examine the source of cash, not only the ending balance.
- U.S. GAAP allows direct and indirect presentations for operating activity.
Why This Financial Report Matters: Cash Flow Statement
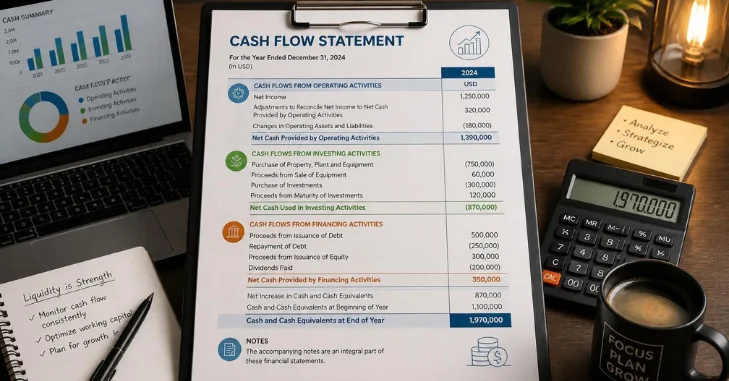
The cash flow statement report explains changes in cash between two balance-sheet dates. It also shows whether normal operations can support payroll, suppliers, taxes, and growth. That makes it useful alongside the income statement and balance sheet.
Profitability and liquidity answer different questions. Under accrual accounting, a company may record sales before customers pay. The business can therefore look profitable while its bank account remains under pressure.
The U.S. Small Business Administration also highlights this problem for growing companies. Receivables and inventory can absorb working capital even while reported profits remain positive. Regular financial reviews help owners catch those pressures earlier.
For broader planning, Business Strategy’s guide to reaching financial goals explains how regular tracking supports better financial decisions.
The Three Sections You Need to Understand
Every statement of cash flows separates movements into operating, investing, and financing activities. Each category answers a different financial question. Together, they explain why the business ended with more or less cash.
Operating activities
Operating activities cover cash connected with the company’s main business activities. Examples include customer collections, supplier payments, payroll, and many routine expenses. This section often deserves an owner’s attention first.
Strong operating results suggest normal business activity is producing usable money. Negative results are not automatically a crisis during one period. Repeated shortfalls deserve closer investigation into pricing, margins, collections, and spending.
Investing activities
Investing activities usually involve long-term assets and investments. Buying equipment normally creates an outflow, while selling equipment can create an inflow. Acquisitions and some investment purchases can also appear here.
A negative investing total does not automatically signal poor performance. A growing company may spend heavily on equipment or facilities. Owners should ask what the spending purchased and whether it supports future operations.
Financing activities
Financing activities explain how a company raises or returns capital. Borrowing can create an inflow, while loan repayment creates an outflow. Owner contributions, share transactions, and distributions may also belong here.
A large financing inflow can make ending cash look strong. That does not mean normal operations created the increase. Owners should separate borrowed or contributed funds from money generated through everyday business activity.
How to Read a Cash Flow Statement
Start with the ending balance, but do not stop there. The source of each increase or decrease matters more than the number itself. A simple review can follow five steps.
- Check the beginning and ending cash balances. Confirm that the ending amount agrees with the related balance-sheet figure.
- Review operating activity first. Determine whether the core business generated or consumed cash during the period.
- Explain major investing movements. Identify equipment purchases, asset sales, acquisitions, or other significant investments.
- Trace financing changes. Look for new debt, repayments, owner contributions, dividends, or similar transactions.
- Compare several periods. One unusual month matters less when the longer pattern remains healthy.
Trends provide more context than one isolated reporting period. A seasonal company may naturally build cash during busy months and use it later. Comparing similar periods can therefore prevent misleading conclusions.
Owners can also compare actual results against forecasts each month. That practice exposes collection delays, unexpected spending, and financing needs earlier. The SBA recommends regular plan-versus-actual reviews as part of business planning.
Direct Method vs. Indirect Method
The direct and indirect methods change how operating activity is presented. They do not change the basic investing and financing categories. U.S. GAAP permits both methods.
| Method | Starting point | What readers see | Main advantage |
| Direct | Major cash receipts and payments | Customer collections and major operating payments | Clear view of actual operating receipts and payments |
| Indirect | Net income | Noncash adjustments and working-capital changes | Clear reconciliation between reported profit and operating cash |
The direct method displays major gross receipts and payments. The indirect method starts with net income and adjusts for noncash items. It also adjusts for changes in accounts such as receivables, inventory, and payables.
U.S. GAAP encourages the direct presentation, although many entities use the indirect approach. Business entities using the direct approach also provide a net-income reconciliation. These requirements help users connect earnings with actual operating cash generation.
Accounting software can make either approach easier to produce consistently. Business Strategy’s business software and services guide covers tools that support financial administration and reporting.
A Simple Small-Business Example
Consider a small U.S. marketing agency. It begins the month with $25,000 and records the movements below. The example focuses on interpretation rather than detailed bookkeeping entries.
| Activity | Amount |
| Beginning cash | $25,000 |
| Net operating activity | +$28,000 |
| Equipment purchases | -$12,000 |
| Net financing activity | +$12,000 |
| Net increase | +$28,000 |
| Ending cash | $53,000 |
The business ends with $53,000, so available cash increased by $28,000. Yet $12,000 of the increase came from net financing activity. An owner should separate operational strength from borrowed money before approving new spending.
The example also shows why the three categories matter. Two companies can reach the same ending balance through different paths. A business funded mainly by operations has a different profile than one that relies heavily on borrowing.
Why Profit and Available Cash Can Differ
Accrual accounting can record revenue before customers pay their invoices. It can also record expenses at different times from the related payment. These timing differences explain why profit and bank balances rarely move together.
Several common events can create a gap:
- Customers take longer to pay outstanding invoices.
- Inventory purchases consume money before the products are sold.
- Equipment purchases use cash without becoming an immediate full expense.
- Loan principal repayments reduce cash without reducing operating profit.
- Owner distributions reduce available money after earnings are calculated.
Depreciation creates the opposite effect. It reduces accounting profit without requiring a current-period cash payment. The indirect method adjusts for noncash items like this during its reconciliation.
For business owners, the lesson is practical. Review profitability and liquidity together before making major commitments. One report explains earnings, while the other explains whether those earnings produced spendable money.
U.S. GAAP Rules Business Owners Should Know
Under U.S. GAAP, the cash flow statement follows ASC 230. ASC 230 separates movements into operating, investing, and financing activities. It also permits direct or indirect presentation for operating activities.
The guidance also addresses noncash investing and financing transactions. Those transactions do not represent actual cash movements during the period. Required GAAP disclosures can still provide readers with information about those activities.
If your company prepares formal U.S. GAAP financial statements, classification details can become technical. Consistency remains important for useful internal management reports. An accountant should review unusual transactions when lender, investor, or reporting requirements apply.
Common Mistakes When Reviewing the Report
Reading only the bottom line can hide important financial problems. A higher balance may come from borrowing instead of stronger operations. A lower balance may reflect productive investment rather than weak performance.
Watch for these common mistakes:
- Treating every positive number as good news.
- Treating every investing outflow as a warning sign.
- Ignoring large increases in receivables or inventory.
- Comparing different seasonal periods without context.
- Assuming reported profit should equal the change in the bank account.
- Failing to reconcile ending cash with the related balance-sheet amount.
Owners should also investigate unusual movements rather than relying on labels alone. A classification tells you what category a transaction belongs to. It does not explain whether management made a sound business decision.
Make the Report Part of Your Monthly Review
Do not treat financial statements as year-end paperwork. Review the three activity sections regularly and investigate large changes while the details remain fresh. Then compare those findings with your budget, balance sheet, and income statement.
This habit can make hiring, purchasing, borrowing, and expansion decisions easier to evaluate. It also gives owners earlier warning when collections or spending move off plan. For more practical business resources, explore Businessstry’s small-business guides.
Frequently Asked Questions
What does a cash flow statement tell you?
It tells you how cash entered and left a company during a defined period. It also explains the net change between beginning and ending balances. Owners can use that information to assess liquidity and funding needs.
What are the three sections of the statement of cash flows?
The three sections are operating, investing, and financing activities. Operating activities cover normal business operations, while investing activities cover many long-term assets. Financing covers borrowing, repayments, owner capital, and similar funding transactions.
Is the direct method better than the indirect method?
Neither method changes the final operating total when prepared correctly. The direct approach shows major receipts and payments more clearly. The indirect approach highlights the connection between net income and operating cash.
How often should a small business review this report?
A monthly review works well for many operating businesses. Quarterly and annual comparisons add useful trend information. Seasonal companies should also compare similar periods across different years.
Can a profitable company still run short of cash?
Yes, because reported income and actual collections can occur at different times. Receivables, inventory, equipment purchases, and debt payments can reduce available money. That is why you should always review profitability alongside liquidity.