

Selling on credit can help a business win customers, but every invoice carries collection risk. Bad debt expense recognizes the portion of receivables that a company expects it will not collect. Recording that loss helps owners avoid overstating income and the value of accounts receivable.
Direct answer: Bad debt expense is the accounting cost of receivables a business expects not to collect. Companies generally estimate expected credit losses through an allowance for financial reporting, while direct charge-offs identify specific unpaid accounts. For U.S. taxes, deductibility depends on worthlessness, prior income inclusion, and the taxpayer’s accounting method.
| Key point | What it means |
|---|---|
| Main purpose | Recognizes expected or confirmed losses from unpaid receivables |
| Income statement effect | Raises operating expenses and reduces net income |
| Balance sheet effect | An allowance can reduce net accounts receivable |
| Common estimation methods | Percentage of credit sales and receivables aging |
| Direct write-off | Removes a specific receivable after it becomes uncollectible |
| U.S. tax issue | Deductibility depends on worthlessness and prior income treatment |
| Main management use | Shows collection risk and supports more realistic financial reporting |
Key Takeaways
- Credit sales create receivables, but not every receivable turns into cash.
- The allowance approach estimates expected losses before individual customers default.
- Aging schedules can produce a more risk-sensitive estimate than one company-wide percentage.
- Writing off an account differs from initially estimating expected credit losses.
- U.S. tax treatment does not always follow financial-reporting treatment.
- Cash-basis businesses generally cannot deduct unpaid income they never reported.
- Collection history should influence future credit policies and loss estimates.
What Is Bad Debt Expense?
Bad debt expense represents the cost associated with customer balances that probably will not be collected. A credit sale initially creates an account receivable because the customer owes the business money. If collection becomes doubtful, accounting records should reflect that reduced economic value.
The issue matters because accounts receivable appears as an asset on the balance sheet. Leaving seriously doubtful invoices at full value can make assets look stronger than they are. It can also make past revenue appear more profitable than the related customer payments support.
Companies that regularly sell on credit should monitor receivables instead of waiting for year-end surprises. Payment patterns, invoice age, disputes, bankruptcies, and customer financial problems can all affect collectibility. The resulting estimates should use evidence that management can support.
Where the Expense Appears on Financial Statements
The expense normally appears on the income statement as an operating expense. Depending on the company’s reporting format, it may appear separately or within a broader operating category. Recording the amount reduces operating income and net income for that period.
Under an allowance approach, the related allowance for credit losses reduces accounts receivable on the balance sheet. The allowance is a contra-asset rather than a separate liability. Cornell University explains that this presentation produces a more realistic expected collectible amount.
An estimated loss does not itself create a cash payment during that period. The underlying problem is that expected customer cash never arrives. Business owners should therefore compare receivable quality with their cash flow statement guide when reviewing liquidity.
How to Calculate Uncollectible Receivables
Businesses commonly estimate credit losses using a percentage of credit sales or an accounts receivable aging schedule. Both methods use historical collection experience, but they approach the estimate differently. Current customer conditions should also inform the assumptions when they materially change expected collections.
Percentage of Credit Sales Method
This method applies an estimated uncollectible percentage to credit sales for the accounting period. Assume a company has $400,000 of credit sales and expects 1.5% to remain unpaid. The estimated expense would equal $6,000.
The formula is straightforward: credit sales × expected uncollectible percentage. The percentage should come from the company’s own collection history whenever sufficient data exists. Management should revise the rate when actual write-offs repeatedly differ from estimates.
This method works well when collection patterns remain reasonably stable across customers. It focuses primarily on matching expected losses with current-period sales. A more detailed approach may work better when invoice age strongly predicts collection risk.
Accounts Receivable Aging Method
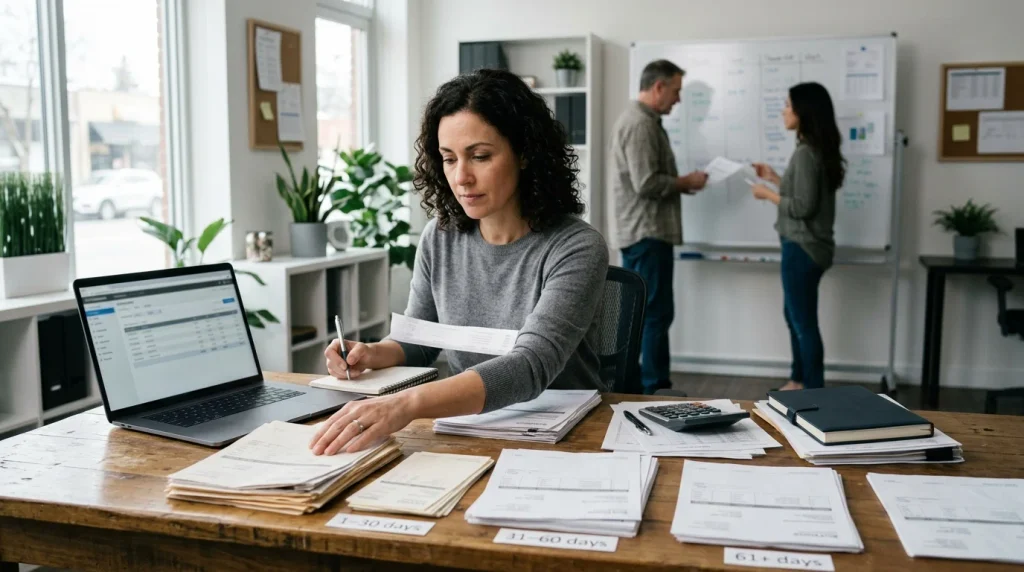
An aging schedule groups receivables according to how long invoices have remained outstanding. A company might use current, 31–60 day, 61–90 day, and over-90-day groups. Older categories usually receive higher estimated loss rates because collection uncertainty often rises with age.
Suppose receivables include $60,000 current, $25,000 aged 31–60 days, and $10,000 aged 61–90 days. Another $5,000 is more than 90 days old. Applying rates of 1%, 3%, 5%, and 10% produces an estimated allowance of $2,350.
This approach focuses on the required ending allowance rather than only current sales. The business compares that target with the allowance balance already recorded. It then records the adjustment needed to reach the updated estimate.
Journal Entries for the Allowance Method
When management records an expected loss, it debits the expense account and credits the allowance account. The receivable from a specific customer remains in accounts receivable at this stage. That distinction matters because no individual invoice has necessarily become worthless yet.
| Account | Debit | Credit |
|---|---|---|
| Uncollectible accounts expense | $6,000 | , |
| Allowance for credit losses | , | $6,000 |
When a specific $1,000 receivable later becomes uncollectible, the company removes it against the allowance. It debits the allowance and credits accounts receivable for $1,000. The company does not record the same expense again during that write-off.
Trade receivables arising from revenue transactions fall within the expected-credit-loss framework under U.S. GAAP. Deloitte’s accounting guidance explains their treatment under the CECL model.
Allowance Method Versus Direct Write-Off
The two approaches differ mainly in timing and purpose. An allowance anticipates expected losses before a specific invoice becomes hopeless. Direct write-off accounting waits until management identifies a particular balance as uncollectible.
| Feature | Allowance approach | Direct write-off |
|---|---|---|
| Timing | Estimates losses before specific defaults | Records loss after identifying an account |
| Related credit | Allowance for credit losses | Accounts receivable |
| Main strength | More timely receivable valuation | Simple treatment of identified losses |
| Financial reporting | Supports expected-loss reporting | Limited usefulness for material estimates |
| Tax relevance | Book treatment may differ from tax | Specific charge-offs matter for U.S. deductions |
For a direct write-off, a $1,000 uncollectible invoice creates a debit to the expense account. Accounts receivable receives the $1,000 credit. This entry removes that particular customer’s balance from the books.
Businesses should not assume their financial-reporting treatment automatically determines federal tax treatment. Accounting standards and federal tax rules have different objectives. A CPA should review material differences for the company’s entity type and reporting requirements.
Why Collection Losses Matter Beyond Accounting
Unpaid invoices affect more than reported profit. They can restrict cash available for payroll, vendors, inventory, taxes, and expansion. A profitable income statement can therefore coexist with weak operating liquidity.
The pattern can also reveal problems in a company’s credit process. Rising losses may indicate weak customer screening, generous payment terms, delayed collections, or excessive concentration in risky customers. Reviewing those trends can support better operating decisions.
Businesses with limited finance staff may need stronger bookkeeping processes as transaction volume grows. Businessstry’s guide to scaling administrative functions discusses accounting support options for growing companies. Its business software and services guide also covers tools that support financial administration.
U.S. Tax Treatment of Uncollectible Business Debts
Federal tax rules require more than labeling an invoice unlikely to be collected. The IRS says a business debt generally must become partly or totally worthless before a deduction applies. Businesses should also document reasonable collection efforts and the circumstances supporting worthlessness.
Accrual-method taxpayers may deduct an uncollectible receivable when the related amount was previously included in income. This rule prevents a taxpayer from deducting an economic loss that never entered taxable income. The IRS describes credit sales to customers as a common source of business debts.
Cash-method taxpayers face a different result for many unpaid service invoices. They generally report income when payment is received, rather than when the invoice is issued. Therefore, they usually cannot deduct unpaid income that was never included in taxable income.
The IRS generally uses the specific charge-off method for deductible business debts, subject to stated exceptions. That tax treatment should not be confused with a financial-statement allowance based on expected losses. Businesses should keep book adjustments and tax adjustments clearly documented.
A Practical Example for a Small U.S. Business
Consider a consulting firm with $300,000 in annual credit sales. Historical records show that roughly 2% of similar receivables eventually become uncollectible. The company could initially estimate a $6,000 expected loss based on those records.
Later, one customer closes and leaves a $1,500 invoice unpaid. If the company previously created an allowance, it can remove that account against the existing allowance. The write-off does not require another $1,500 operating expense at that moment.
For federal taxes, the result depends on the firm’s accounting method and the facts supporting worthlessness. An accrual taxpayer may have previously reported that receivable as income. A cash taxpayer may never have included the unpaid $1,500 in taxable income.
How to Reduce Future Credit Losses
Better collections start before an invoice becomes overdue. A business can define credit limits, check new customers, state payment terms clearly, and invoice promptly. Those controls reduce preventable collection problems without eliminating normal commercial risk.
Owners should also review receivables by age at least monthly. Large balances moving into older aging categories deserve attention before communication becomes difficult. Consistent follow-up usually gives management better information about which amounts remain collectible.
When evaluating another company, receivable quality also deserves close scrutiny. Buyers should verify aging schedules, customer concentration, write-off history, and collection trends during financial due diligence. Businessstry’s guide to buying a business explains why verifying financial records matters before closing an acquisition.
Frequently Asked Questions
What is bad debt expense in simple terms?
Bad debt expense is the accounting cost of money customers owe but a business does not expect to collect. It prevents doubtful receivables from making reported financial results look stronger than economic reality. The exact recording method depends on the company’s accounting and reporting requirements.
Is an allowance the same as a write-off?
No, an allowance estimates expected losses before specific accounts necessarily fail. A write-off removes a particular customer balance after the business determines collection is no longer expected. Under an allowance system, that later removal normally reduces the existing allowance.
Does an uncollectible invoice reduce cash flow?
The accounting entry itself does not send cash out of the bank account. The cash problem exists because expected customer money never arrived. Persistent unpaid invoices can therefore weaken liquidity even when reported sales remain strong.
Can a U.S. business deduct every unpaid invoice?
No, federal deductibility depends on the business’s accounting method and whether the debt meets IRS requirements. Accrual taxpayers may qualify when an uncollectible amount was previously included in income. Cash taxpayers generally cannot deduct unpaid income they never reported.
When should a business review its allowance?
A company should review its estimate at each relevant reporting period. It should compare actual write-offs with prior assumptions and inspect changes in invoice aging. Material changes in customers or economic conditions may justify revising the estimated loss rates.
Turn Receivable Data Into Better Decisions
Uncollectible accounts should be treated as a management signal, not merely a year-end bookkeeping adjustment. Track aging, compare actual losses with estimates, and investigate customers whose payment patterns deteriorate. Those habits produce more useful financial statements and earlier warnings about collection problems.
Keep tax treatment separate from financial-reporting estimates because the rules serve different purposes. Maintain support for collection efforts, write-offs, and estimation assumptions. For material amounts or uncertain tax treatment, have a qualified U.S. accountant review the entries and deductions.
—–